QSBS Section 1202 Explained for Startup Founders (2025 Rules)
QSBS can make a founder’s sale far cheaper in tax. Here are the numbers and dates from a Cooley cheat sheet.
Key takeaways:
- For stock acquired after July 4, 2025: 50% exclusion at 3 years, 75% at 4 years, 100% after more than 5 years.
- The per-shareholder cap is the greater of $15 million or 10 times basis; the gross asset limit is $75 million.
- Older stock uses a $10 million cap and a $50 million asset limit.
- The issuer must be a C corporation.
1. What QSBS is
Qualified small business stock (QSBS) under Section 1202 lets eligible shareholders exclude part or all of the gain when they sell stock in a qualifying small C corporation, if they meet holding-period and other requirements. For founders, it is one reason entity type and the date shares are issued matter. This article summarizes the rules in a Cooley cheat sheet; it is not tax advice.
2. The 2025 change in numbers
The rules depend on when the shares were acquired. For stock acquired after July 4, 2025, Cooley lists:
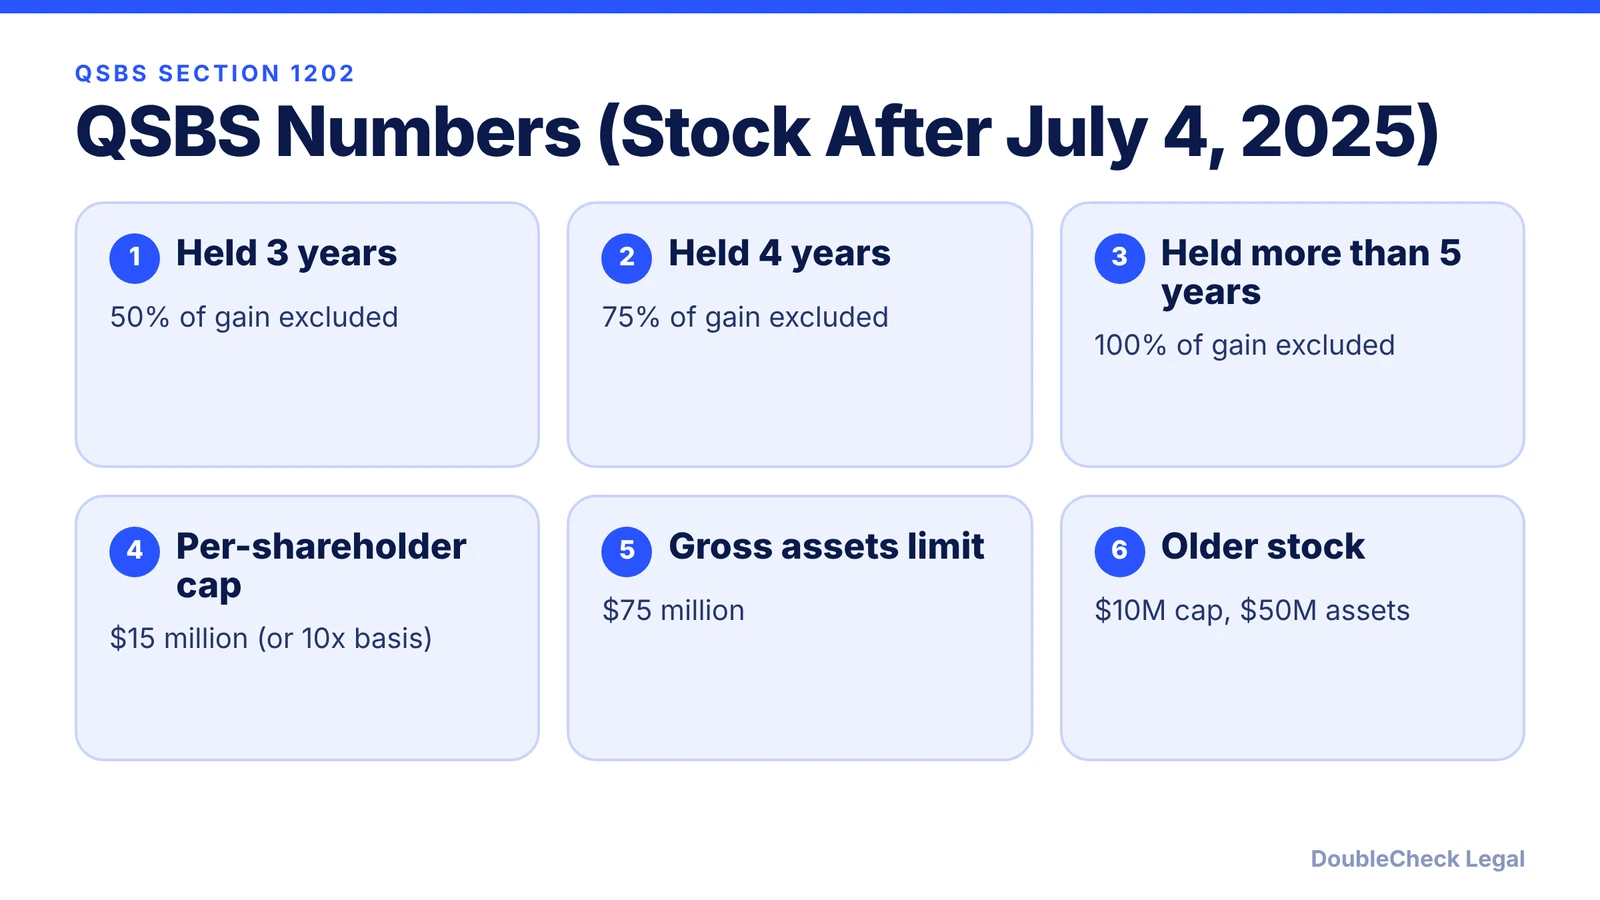
- The excludable gain is capped at the greater of $15 million (reduced by amounts excluded in prior years from the same company) or 10 times the shareholder’s aggregate adjusted basis in the company’s QSBS.
- The company’s aggregate gross assets (adjusted tax basis) must be at or below $75 million at all times after August 10, 1993, and immediately after the issuance. Cooley notes the $75 million figure is adjusted for inflation starting in 2027.
- Older stock uses the $10 million cap and $50 million asset limit.
3. Older stock
For stock acquired before the July 2025 change, the exclusion depends on the acquisition date: 50% after more than five years for stock acquired before February 18, 2009; 75% after more than five years for stock acquired February 18, 2009 to September 27, 2010; and 100% after more than five years for stock acquired after September 27, 2010.
4. Timeline for a founder
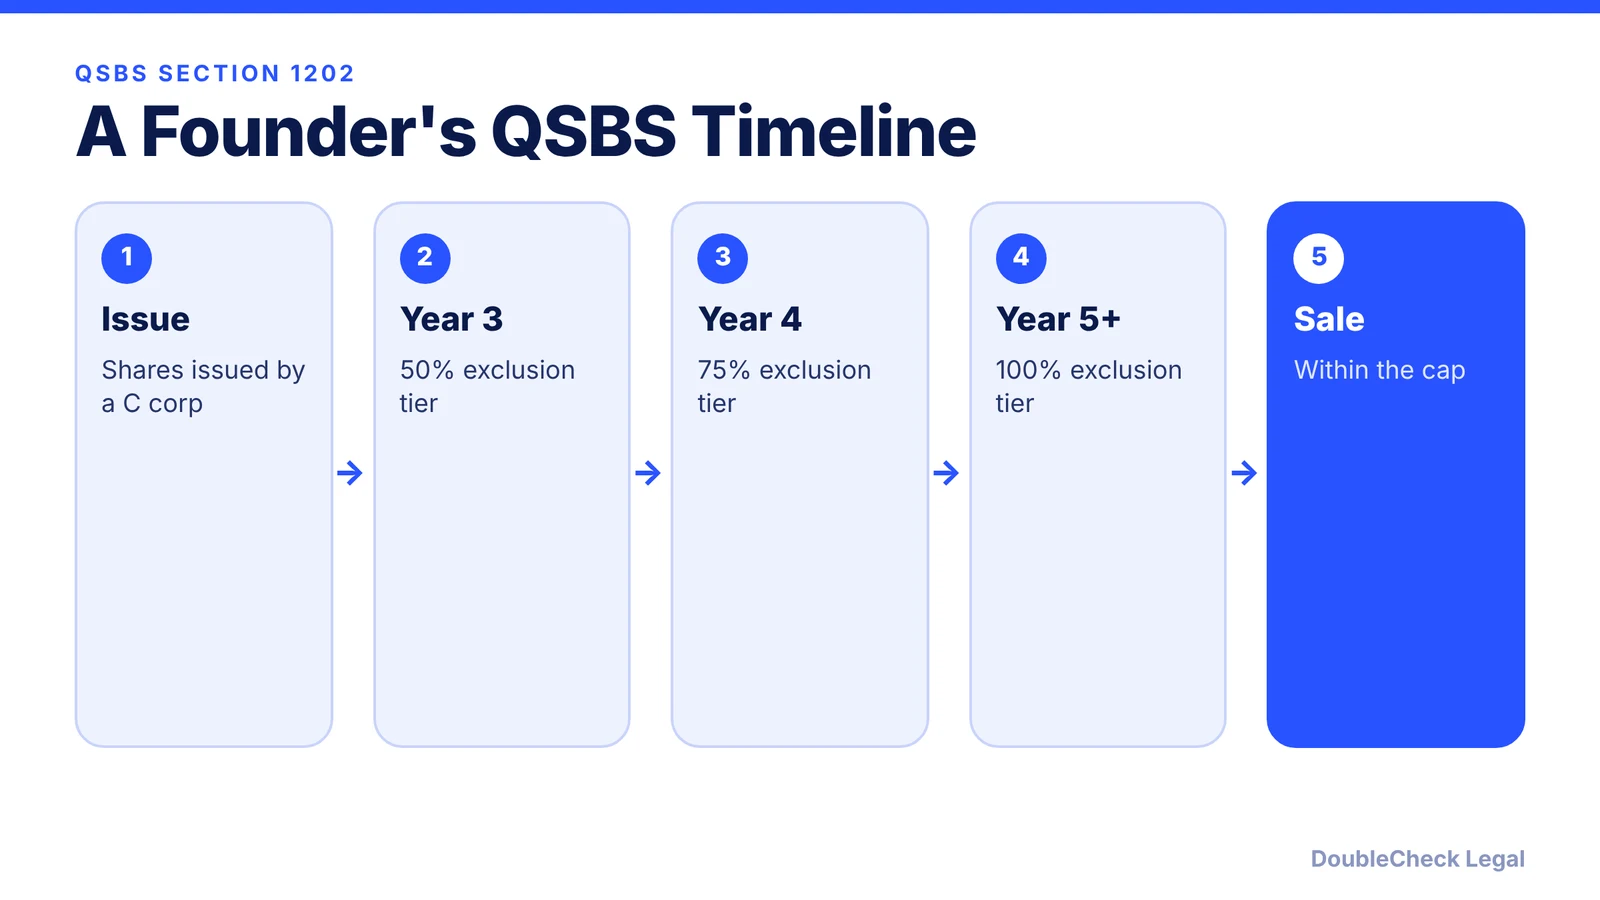
Founder stock timing interacts with vesting and the 83(b) election; ask a tax professional how your facts fit.
5. What can break it
Cooley cautions that significant redemptions, reorganizations, or conversions can compromise QSBS treatment. See the qualification checklist for the C corporation, original issuance, and active business tests.
6. Why this affects your entity choice
Because QSBS requires a C corporation, an LLC taxed as a partnership is not eligible. Read LLC vs. C corp for startups and S corp vs. C corp for venture-backed startups.
Where DoubleCheck fits
DoubleCheck is built for businesses that start legal work with AI. Bring your question or draft, use an AI-first workflow to understand and verify it, and when professional advice is warranted, you can connect with an independent attorney. Attorneys on DoubleCheck are independent professionals; an attorney-client relationship forms only if an attorney accepts your engagement.
Sources: Cooley: Qualified small business stock cheat sheet.
FAQ
What is QSBS?
Qualified small business stock under Section 1202, which can let eligible shareholders exclude part or all of the gain on sale if they meet the requirements.
What changed after July 4, 2025?
For stock acquired after that date, Cooley lists tiered exclusions at 3, 4, and 5 years, a $15 million cap, and a $75 million gross asset limit.
Does an LLC qualify?
The issuer must be a C corporation; pass-throughs are not eligible, per Cooley.
Is this tax advice?
No. Confirm how the rules apply to your facts with a tax professional.
General information only. This article is not legal, tax, investment, or accounting advice.